Is your hot work actually covered? Kingsbridge Contractor Insurance provides 5 insurance checkpoints for heating contractors to be aware of.
As temperatures drop and householders turn their heating back on, gas and heating engineers are entering their peak season, but high workload can bring increased risk on site. Kingsbridge Contractor Insurance is urging gas and heating engineers to look beyond their policy limits and pay urgent attention to on-site compliance conditions, particularly when working with heat.
The specialist trade and contractor insurance experts at Kingsbridge warn that carrying insurance cover is only part of the risk management picture. The company says that when completing higher-risk work involving heat application, failing to follow specific policy warranties can leave self-employed engineers and contractors facing unpaid claims.
“Engineers shouldn’t assume that simply holding an active insurance policy means every hot-work activity is automatically covered,” says Max Bennett, Head of Schemes at Kingsbridge Contractor Insurance. “When you’re using soldering irons, blowtorches, or heat guns, underwriters attach specific conditions to your policy. If an incident occurs and those conditions weren’t met on-site, a claim can easily be declined.”
Max urges gas engineers to review five key policy checkpoints:
– Hot-Work Permits & Conditions: Depending on the policy and the work being carried out, there may be specific requirements around hot works. Engineers shouldn’t assume that simply having insurance means every activity is automatically covered, so it’s important to check what conditions apply before starting work.
– Fire precautions during and after the job: It’s easy to focus on the immediate risk while heat is being used, but precautions may need to extend beyond the point the work finishes. Things like removing combustible materials from the area and having appropriate fire-extinguishing equipment on hand need to be considered.
– Understanding exclusions and limitations: Engineers should be clear on exactly what activities their policy covers. If the nature of their work has changed, or they’ve started taking on jobs involving different or higher-risk activities, their existing cover may not necessarily reflect that.
– Subcontractor Exposure: Another area worth checking is how a policy treats work carried out by subcontractors. Businesses shouldn’t automatically assume everyone working on a job is protected in exactly the same way under their own insurance arrangements.
– Proactive Insurer Updates: More broadly, if the type, scale or risk profile of the work a business carries out changes, it’s worth speaking to their insurer or broker rather than waiting until something goes wrong to discover there was a gap.
Bennett adds: “A quick five-minute review of your policy conditions could be the difference between a rejected claim or invalidated policy versus a full payout should an incident happen on site.”
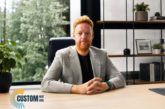
Image: Max Bennett, Head of Schemes at Kingsbridge Contractor Insurance (Kingsbridge Contractor Insurance)